Forklift Finance Guide for Gold Coast Warehouses & Distribution Businesses
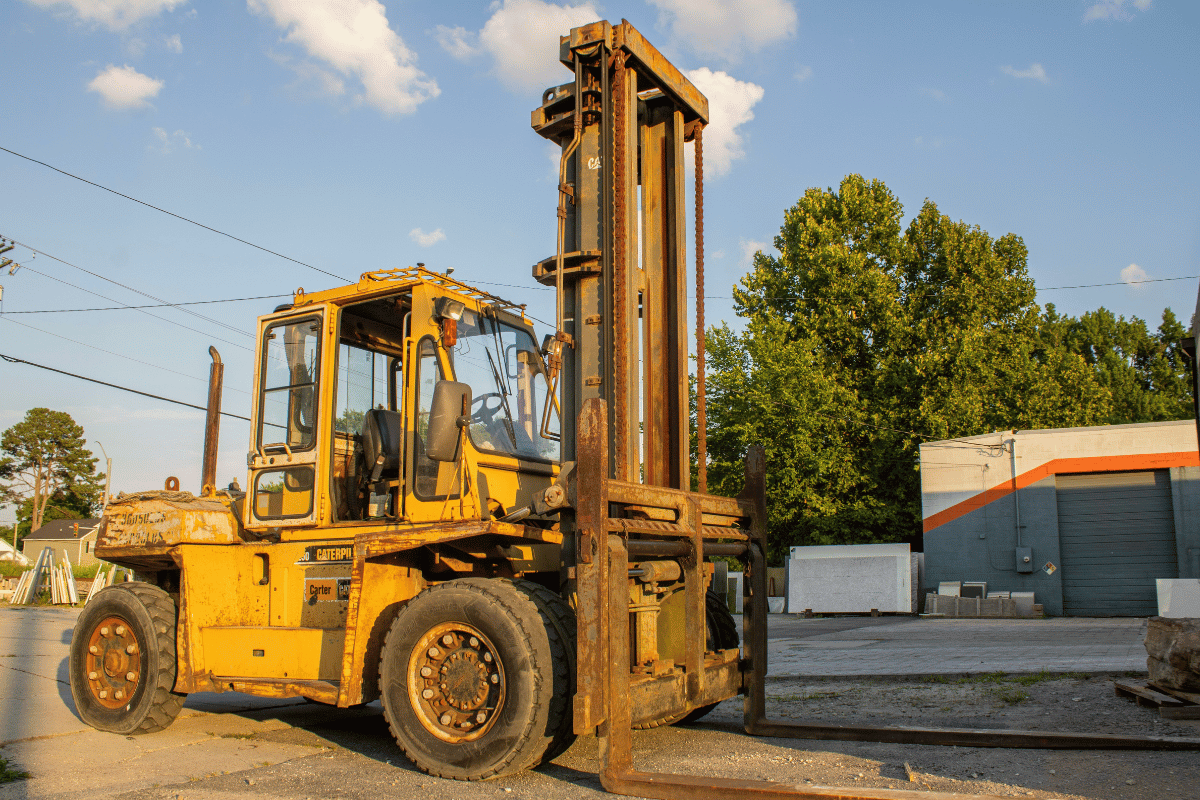
If you run a warehouse or distribution centre on the Gold Coast, your forklifts do more of the heavy lifting than almost any other asset you own. Whether you are moving pallets in Yatala, loading trailers in Ormeau or running a growing fulfilment operation in Arundel, a forklift that is out of action, or simply the wrong fit, slows down everything else.
The catch is that a quality forklift is a significant outlay, and that is before you add attachments, chargers, safety features and operator training. This guide walks through the main ways Gold Coast warehouses and distribution businesses fund forklifts, what to weigh up before you sign, the tax and licensing points worth knowing, and where Millard Financial can help across the rest of your operation.
Why Finance a Forklift Instead of Paying Cash?
Paying outright can feel like the simple option, but it ties up money that a warehouse business usually needs elsewhere. Financing lets you:
- Preserve working capital for stock, wages, rent and unexpected costs
- Match repayments to the revenue the equipment helps you earn
- Scale for peak periods without draining your reserves
- Keep your budget predictable with fixed, scheduled repayments
- Keep other credit lines free for when you need them
Your Main Forklift Finance Options
Chattel mortgage. You take ownership of the forklift from day one, and the lender holds a mortgage over it until the loan is paid out. Many businesses like the simplicity of owning the asset from the start, and depending on your circumstances there may be GST and deduction benefits, so it is worth confirming with your accountant. Our guide to chattel mortgages covers how they work in more detail.
Finance lease. The lender owns the machine and you make regular payments to use it. At the end of the term you typically have options, such as paying out the residual, refinancing, upgrading or returning the asset. This structure can suit businesses that like to cycle equipment every few years. If you are weighing up the two approaches, our guide to finance versus leasing explains the trade-offs (it is written for heavy vehicles, but the principles carry across).
Hire or rental. Short-term hire is useful for seasonal peaks, trialling a machine or covering a breakdown. You do not own the asset, and over a long period it is usually the most expensive way to run a forklift, so it tends to work best as a stop-gap rather than a long-term plan.
Working capital support. If a forklift purchase lands during a stock build-up or a big contract ramp, a cash flow lending facility can help you keep cash on hand while you invest in equipment.
New or Used: What to Weigh Up
New forklifts usually come with a warranty, the latest safety and efficiency features, and lower maintenance costs in the early years. The trade-off is a higher purchase price and faster early depreciation.
Used forklifts can stretch your budget further, but you need to look closely at hours of use, service history, and the condition of the mast, chains, tyres and forks. Lenders often apply their own age and condition limits to used equipment, and these vary from lender to lender. Buying from a dealer generally makes for a smoother assessment than a private sale.
Electric, LPG or Diesel: Why Power Type Affects Your Finance
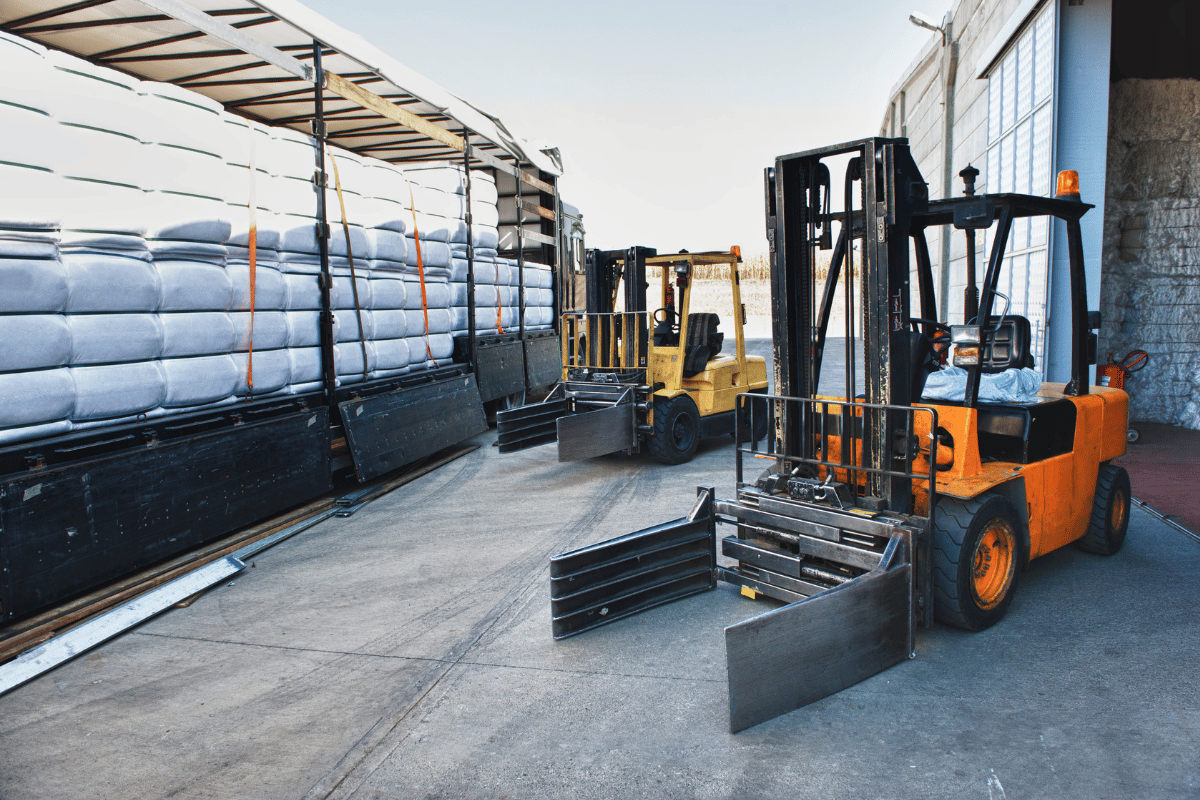
Electric forklifts (including lithium-ion models) suit indoor, high-throughput warehouses, but you may need to budget for charging infrastructure and electrical capacity. LPG and diesel machines tend to suit outdoor yards and heavier duty cycles.
When you collect quotes, ask what is included so you can plan your finance around the full package, not just the truck. Batteries, chargers, attachments such as side-shifters, and safety extras like blue lights or cameras can add up quickly. It is worth asking early whether these can sit on the same invoice and the same finance contract.
Term, Residual and Balloon Payments
The finance term should reflect how long you realistically plan to keep the machine. A shorter term means higher repayments but less interest overall. A longer term lowers your repayments but increases the total cost.
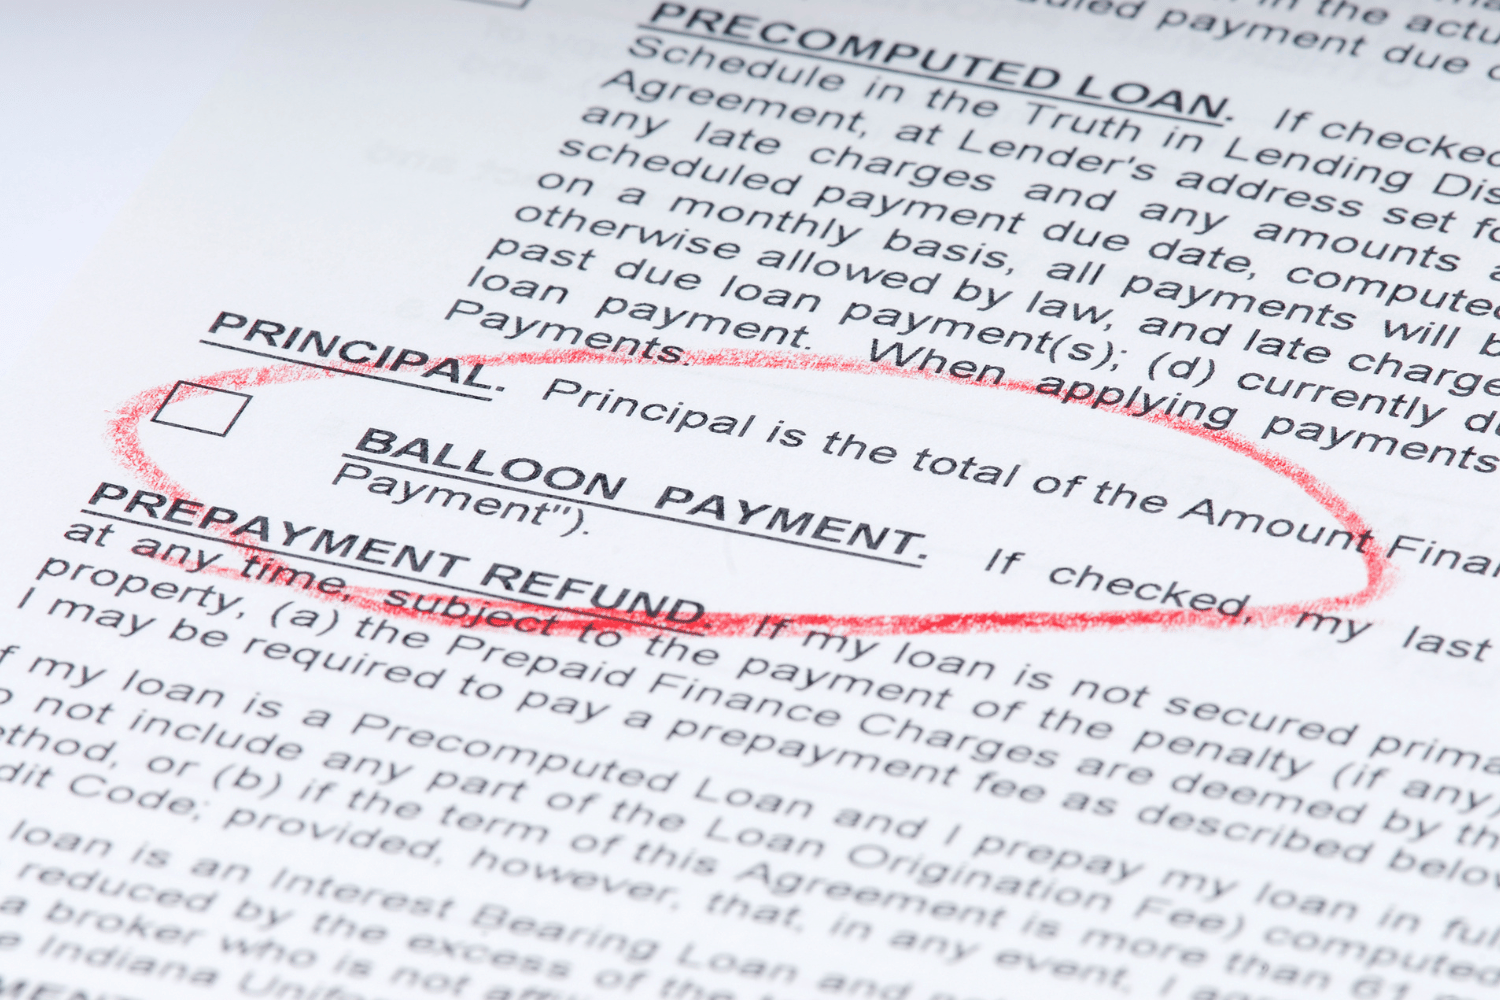
A balloon or residual can reduce your regular repayments further, but it leaves a lump sum due at the end of the term. If you are considering that structure, read our explainer on balloon payments on equipment loans first. It is also worth understanding what affects equipment finance interest rates and whether a fixed or variable rate suits your business.
Tax Considerations for Warehouse Equipment
Tax can influence both what you buy and when you buy it. From 1 July 2026, small businesses with an aggregated turnover under $10 million can generally claim an immediate deduction for eligible depreciating assets costing less than $20,000 that are first used or installed ready for use in the income year. The ATO's instant asset write-off guidance sets out the eligibility rules in full.
Whether a particular forklift qualifies depends on its price, when it is ready for use and your business circumstances. Assets above the threshold are generally depreciated over time instead. For a broader look at timing, see our guide to the instant asset write-off and EOFY planning, and always confirm the treatment with your accountant.
Operator Licensing and Safety Costs
Finance gets the machine onto your warehouse floor, but your team also needs to be authorised to drive it. In Queensland, forklift work generally requires a high risk work licence. Workplace Health and Safety Queensland explains that an LF licence covers forklift trucks, while a separate LO licence is needed to operate order-picking forklifts. Pedestrian-operated trucks and pallet trucks fall outside the forklift definition.
Check the full requirements on the WorkSafe Queensland forklift licence page, and build training, licensing and refresher costs into your budget alongside servicing, inspections and insurance.
What Lenders Will Want to See
Requirements vary by lender and loan size, but most applications are smoother when you have the following ready:
- Your ABN or ACN and business details
- Recent BAS, financial statements or bank statements
- A supplier quote or invoice with the make, model, year and serial number (plus hours of use for used equipment)
- Identification for directors and guarantors
- Details of any existing business debts
If your warehouse is new, our start-up business loans are built for businesses without a long trading history.
Common Forklift Finance Mistakes to Avoid
- Comparing only the repayment. Look at total cost, fees, residual and flexibility as well.
- Stretching the term beyond the machine's useful life. You do not want to be paying off equipment you have already replaced.
- Forgetting ongoing costs. Servicing, inspections, insurance, batteries and training all sit on top of your repayments.
- Skipping the residual plan. Know how you will handle any lump sum before you sign.
- Approaching a single lender. Different lenders have different appetites for different assets, which is where a commercial finance broker can save you time.
Beyond the Forklift: Where Millard Financial Can Help
We want to be upfront: forklifts are not one of the specific asset categories listed on our equipment finance pages. Where we can help is with the assets that keep a Gold Coast distribution business moving around the warehouse and out the door:
- Truck and commercial vehicle finance for rigid trucks, prime movers, vans and utes covering linehaul, distribution and last-mile delivery
- Heavy equipment finance for excavators, wheel loaders and skid steers, which are handy for yard work, bulk materials and site operations
- Manufacturing machine finance for conveyor systems, packaging equipment and production line machinery
- Asset finance and equipment finance more broadly, including for growing fleets
Our network includes more than 50 lenders, and clean applications can often be approved within 24 to 48 hours. If you are planning a purchase that includes a forklift alongside trucks or loaders, get in touch and we will be upfront about how we can assist. For a wider look at fitting out a facility, you can also read our warehouse equipment finance guide.
Frequently Asked Questions
Can I finance a used forklift?
Often, yes, though it depends on the lender. Age, condition, hours of use and whether the sale is through a dealer or a private seller all influence the assessment.
Do I need a deposit?
It varies. Established businesses with strong cash flow may be able to access lower or no deposit options, while newer businesses or older equipment often require a contribution.
Is it better to finance or hire a forklift?
Hire suits short-term or seasonal needs. If the forklift is a core part of your daily operation, financing usually makes more sense over the long run because you are building towards ownership or a planned residual.
Do my operators need a licence in Queensland?
Generally, yes. Forklift work in Queensland typically requires a high risk work licence, with LF and LO classes covering different types of forklift. Check the WorkSafe Queensland page linked above for current requirements.
Can a new warehouse business get equipment finance?
Possibly. Lenders will look at your industry experience, deposit and overall position. Our start-up business loans page explains what is available to newer operators.
Does Millard Financial finance forklifts?
Forklifts are not one of the asset categories listed on our equipment finance pages. Our focus is trucks and commercial vehicles, and heavy equipment such as excavators and loaders. Contact us to discuss your situation and we will be upfront about how we can help.
Talk to Millard Financial About Your Warehouse or Distribution Finance
Whether you are expanding your delivery fleet, adding a loader for your yard or planning a broader equipment upgrade, our team can help you structure finance that fits how your business actually runs. Get in touch with Millard Financial for an obligation-free chat.
This article is general information only and is not financial, tax or legal advice. Your full financial situation would need to be reviewed prior to acceptance of any offer or product.
Latest insights and trends

Ready to secure your finance solution?
Licensing statement:PENNY ENTERPRISES PTY LTD has been appointed as a Corporate Credit Representative of Connective Credit Services.
The Corporate Credit Representative Number (CRN) for PENNY ENTERPRISES PTY LTD is 566212 Australian Credit Licence 389328 Disclaimer statement: Disclaimer: Your full financial situation would need to be reviewed prior to acceptance of any offer or product.
Member of FBAA Finance Brokers Associate Australia Member of AFCA Australian Financial Complaints Authority